Medicare at 65+: Make Your Coverage Count
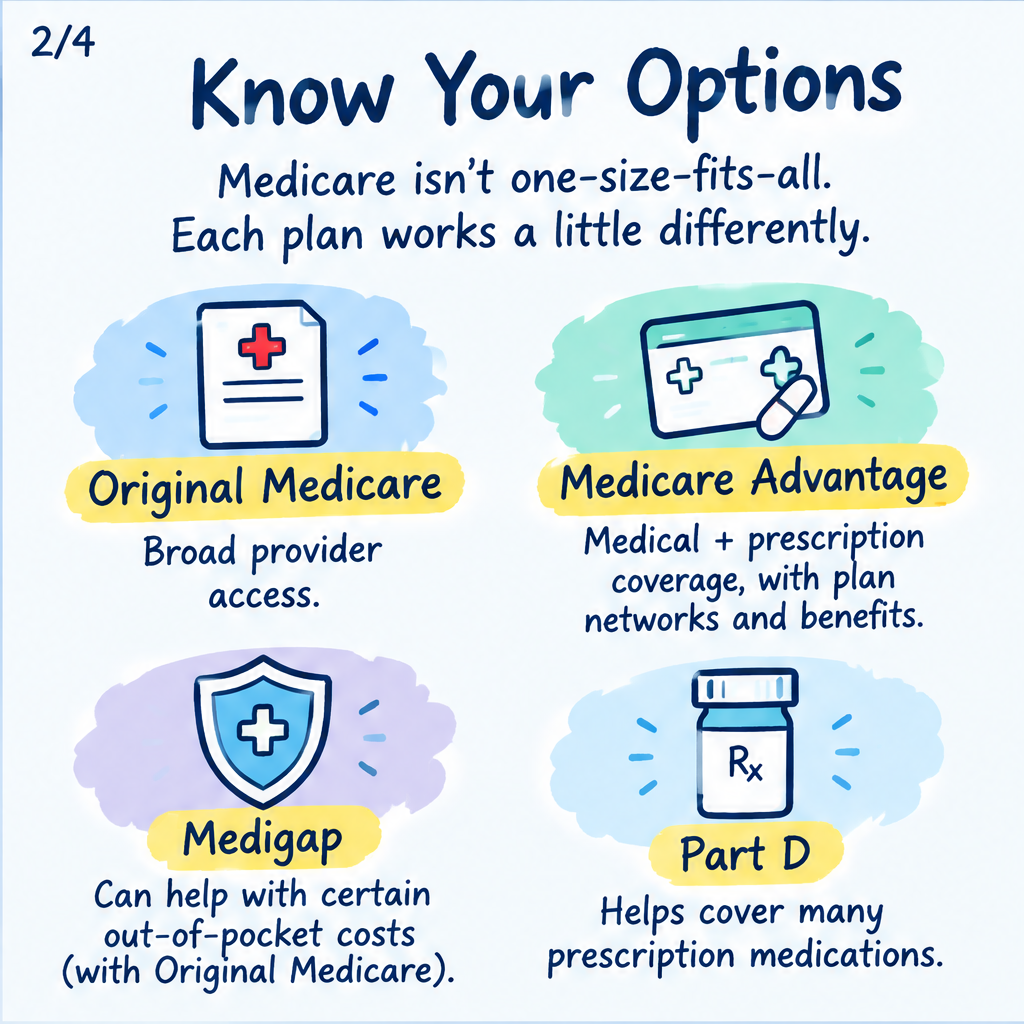
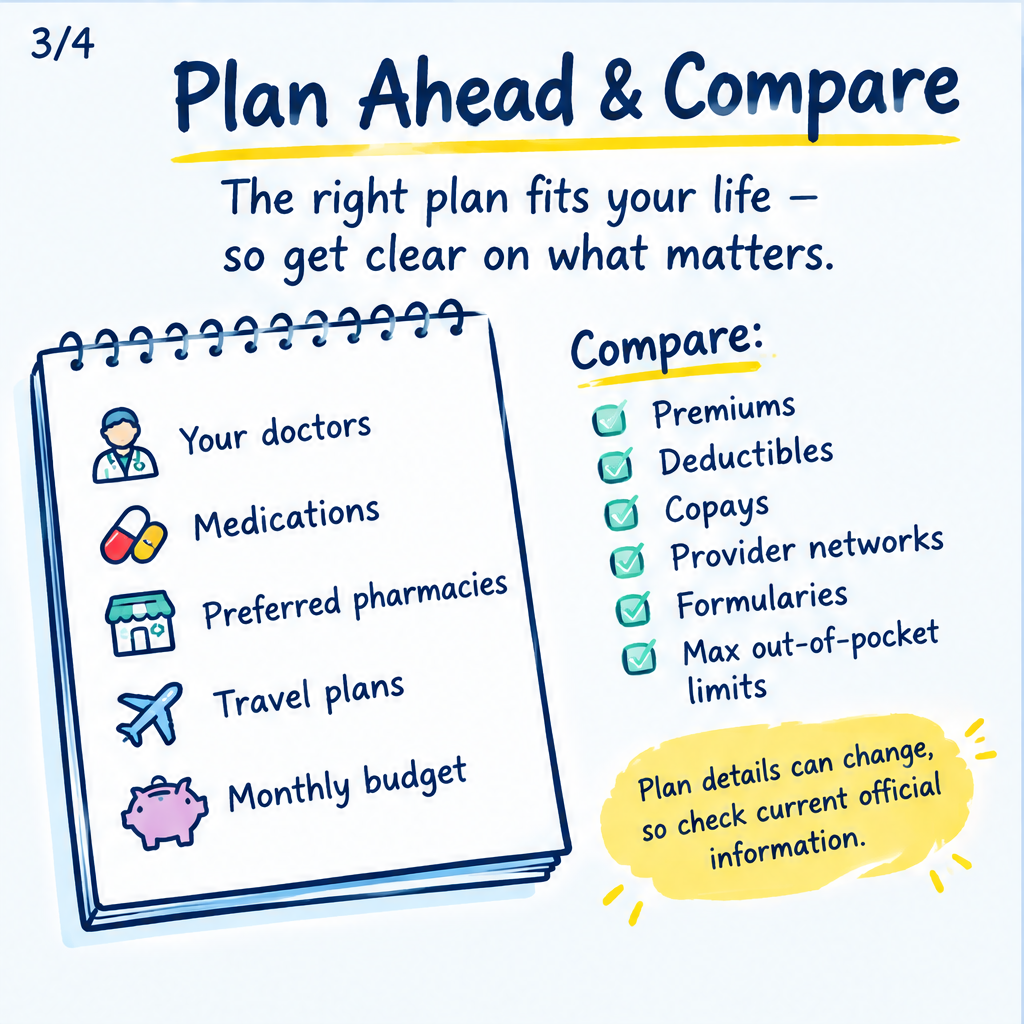
Turning 65 is an important Medicare milestone, and understanding your choices early can make the process easier. Most people should review their Initial Enrollment Period around age 65 to reduce the risk of delayed coverage or late-enrollment penalties. Your timing may differ if you have qualifying employer coverage, so confirm the rules that apply to your situation. Medicare decisions are personal. Original Medicare may offer broad provider access, while Medicare Advantage plans often combine medical and prescription coverage with plan-specific networks and benefits. Medigap policies can help with certain out-of-pocket costs when paired with Original Medicare, and Part D helps cover many prescription medications. Before choosing coverage, list your doctors, medications, preferred pharmacies, travel plans, and monthly budget. Compare premiums, deductibles, copays, provider networks, formularies, and maximum out-of-pocket limits. Plan details can change, so review current official information and confirm benefits directly. Ready to take the next step? Prepare your questions and personal details, then consult Medicare.gov or a licensed insurance professional for guidance tailored to your needs. This content is educational and is not a substitute for official Medicare advice or a personal coverage recommendation.